For Lenders
Help your borrower with the mobile home installation and the land.
Contractors for your borrower, free to them, and a Land Check on the land they want.
Get a free quote for your mobile home installation.
We line up your borrower's contractors, free to the borrower: I call them myself and learn more about their project and answer any questions they have. Their number is never sold. Contractors do mobile-home work and are checked by us.
Have a borrower ready? Call now or reply with your borrower's name and number and I'll call them.
Know the land before the loan moves forward
Give your borrower a written view of the land records before the next commitment.
Your report pulls everything on record about this land and reads it for a mobile home: zoning, deed and subdivision restrictions, flood zone, soil and septic, access, topography. You'll know what clears, what will cost more, and the one question only the county can answer — with the office, the contact and the question written for you.
Your borrower orders the Land Check through your link.
One property, one request, one report
Everything on record about this land, read for a mobile home — what clears, what costs more, and exactly who at the county to ask.

Put the site questions beside the loan file
Use the report before the buyer commits to the land or home. It brings available public records, dated sources, missing information, and next steps together so an unresolved site condition can get attention while there is still time to act.
- Zoning
- The governing jurisdiction, available rules for the proposed mobile home, and any conditions or permission questions to resolve.
- Setbacks and placement
- Published placement requirements and the information still needed to check the intended home location against them.
- Flood
- Available mapped flood information and the questions that may change the proposed location or site work.
- Septic and water
- Available septic and well records, the proposed water and wastewater route, and missing evaluations or capacity confirmations.
- Access
- Available access records and potential transport constraints for the transporter or relevant record source to confirm.
- Permits
- The responsible offices, relevant published requirements, and the approvals still needed for the proposed project.
Each finding distinguishes what the available evidence supports from what still needs confirmation. An absent record stays an open question.
Will this land hold up the loan?
Will this land take a mobile home? Zoning, setbacks, flood and road access; septic, well and the permit path — read before your borrower buys, reviewed by an experienced mobile home setup contractor and dealer.
Will this slow down my closing?
Your borrower orders it before committing to the land. The point is to find site questions while there is still time to act on them.
Is the home even allowed on this parcel?
The report reads the county’s zoning and placement rules for the proposed home and flags any permission or condition still open. Where a rule is unclear, it says so and names the office that decides. It is research, not the county’s determination.
Does the land have legal road access, and who maintains the road?
The report checks road frontage and the access records it can find, and flags a private road or a missing access record. Frontage on a map is a clue, not a legal right; the deed, easement or road-maintenance agreement still goes to your title review.
Can the site handle septic and water?
The report gathers the septic and well records it can find, screens the soil, and lists what is still missing. A soil screen is not a septic permit; any approval or test your program requires still comes from the county or the field.
Is it in a flood zone, and will flood insurance be required?
The report shows the mapped flood information for the home site and flags anything that could change where the home sits. It is not your flood determination or an elevation survey; your determination decides insurance.
Will the foundation and site work meet our program?
The report reads the slope and ground and flags questions for the foundation, drainage and driveway. It does not certify a foundation; any engineer’s certification or completion evidence your program asks for comes from the field.
Will it catch a title problem?
Parcel records can show a mismatch in owner, acreage or address, and the report flags one when it finds it. It is not a title search or opinion; your closing attorney or title company resolves title.
Does it tell us whether a used home qualifies?
No. The report covers the land the home is going to. A used home’s history, condition and any additions need the home’s own records and inspection for your review.
Can it confirm the property fits our program’s area or leased-lot rules?
No. It identifies the exact parcel so you can check it against your program’s eligible-area rules. It does not review a lot lease or decide eligibility.
Who pays, and does anything come back to us for the referral?
The Land Check is paid by the buyer, per property. No money ever goes to a lender or realtor for a referral.
Read a real one
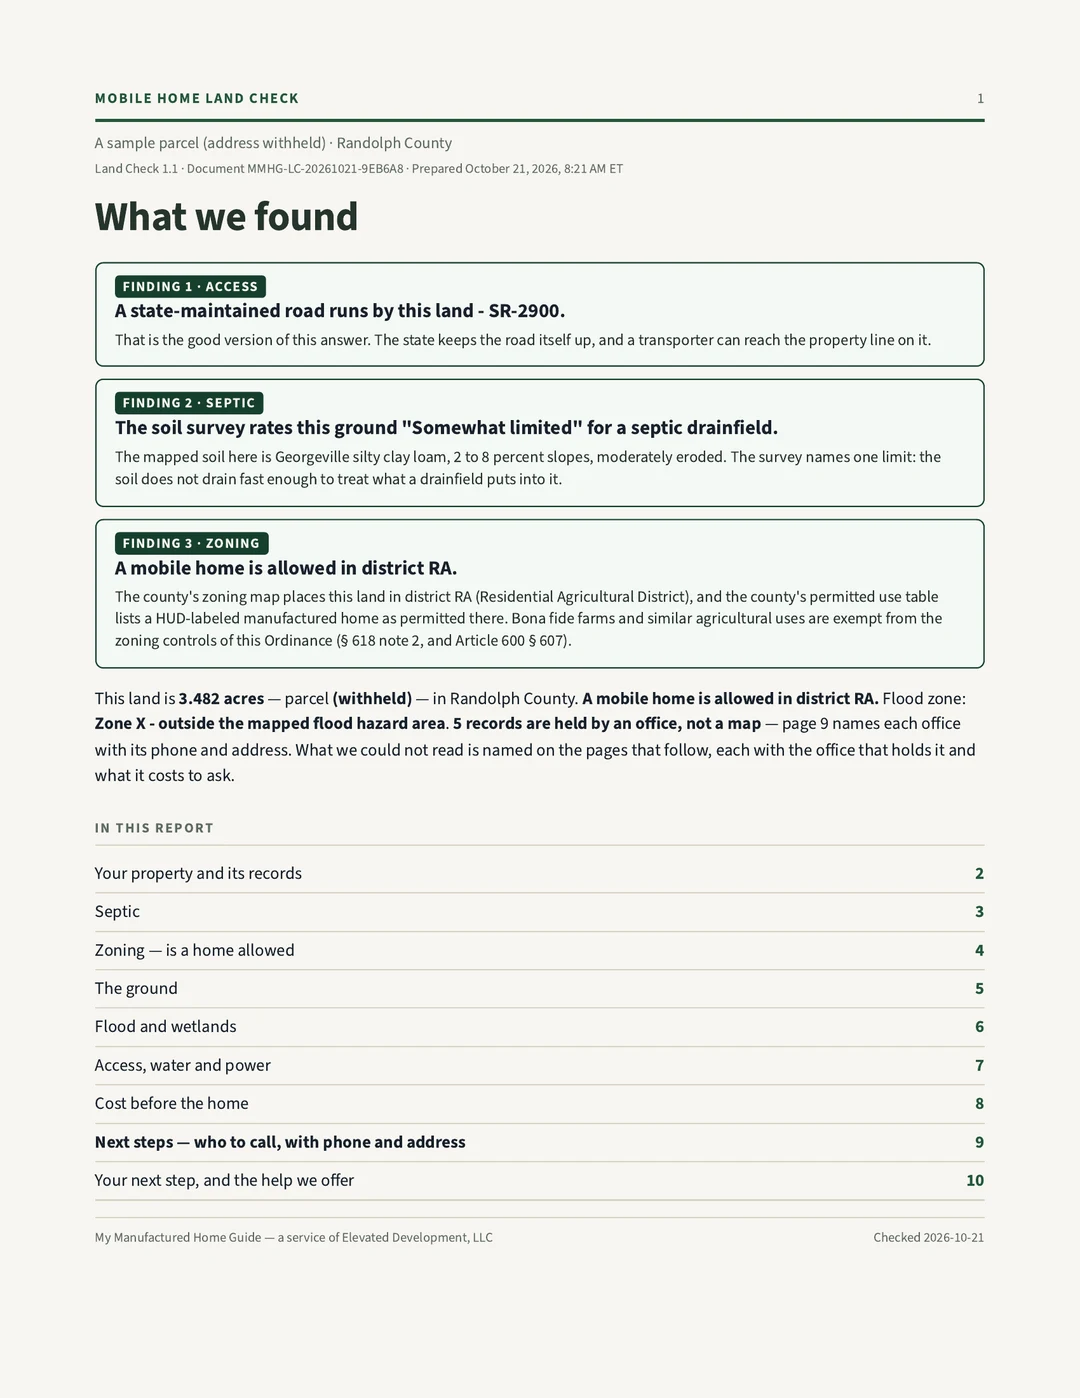
A full Land Check on 3.48 acres in Randolph County. Not a customer's land. Page 1 gives three findings; the rest shows septic, zoning, the ground, flood, access, cost, and who to call.
Open the sample report (PDF, 10 pages)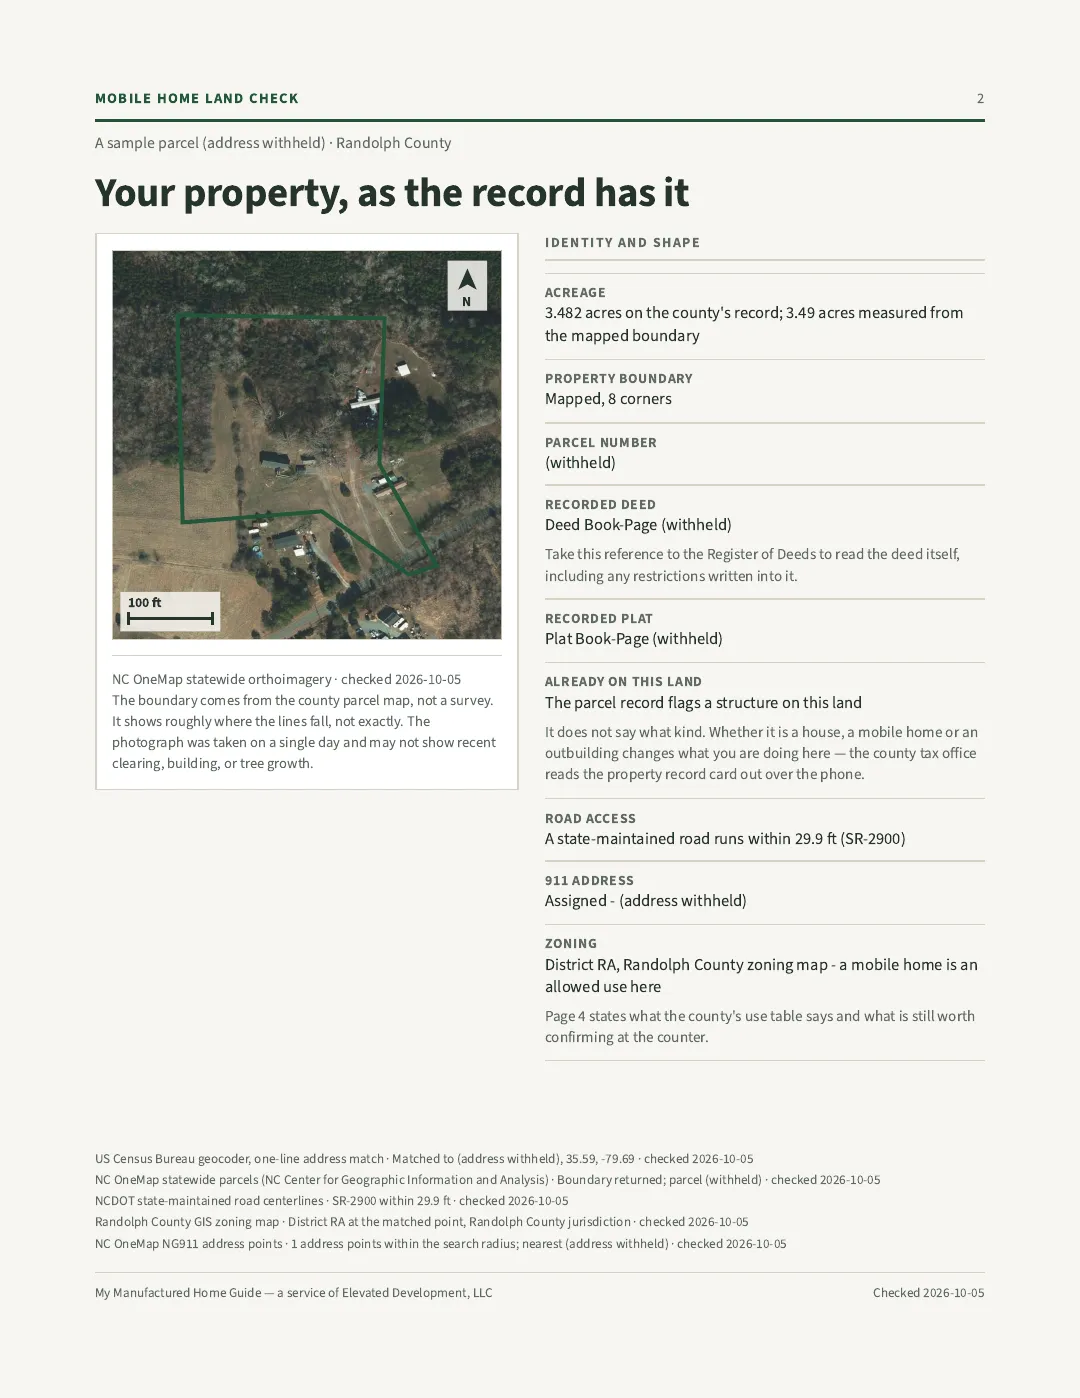
Page 2 — the parcel on the aerial
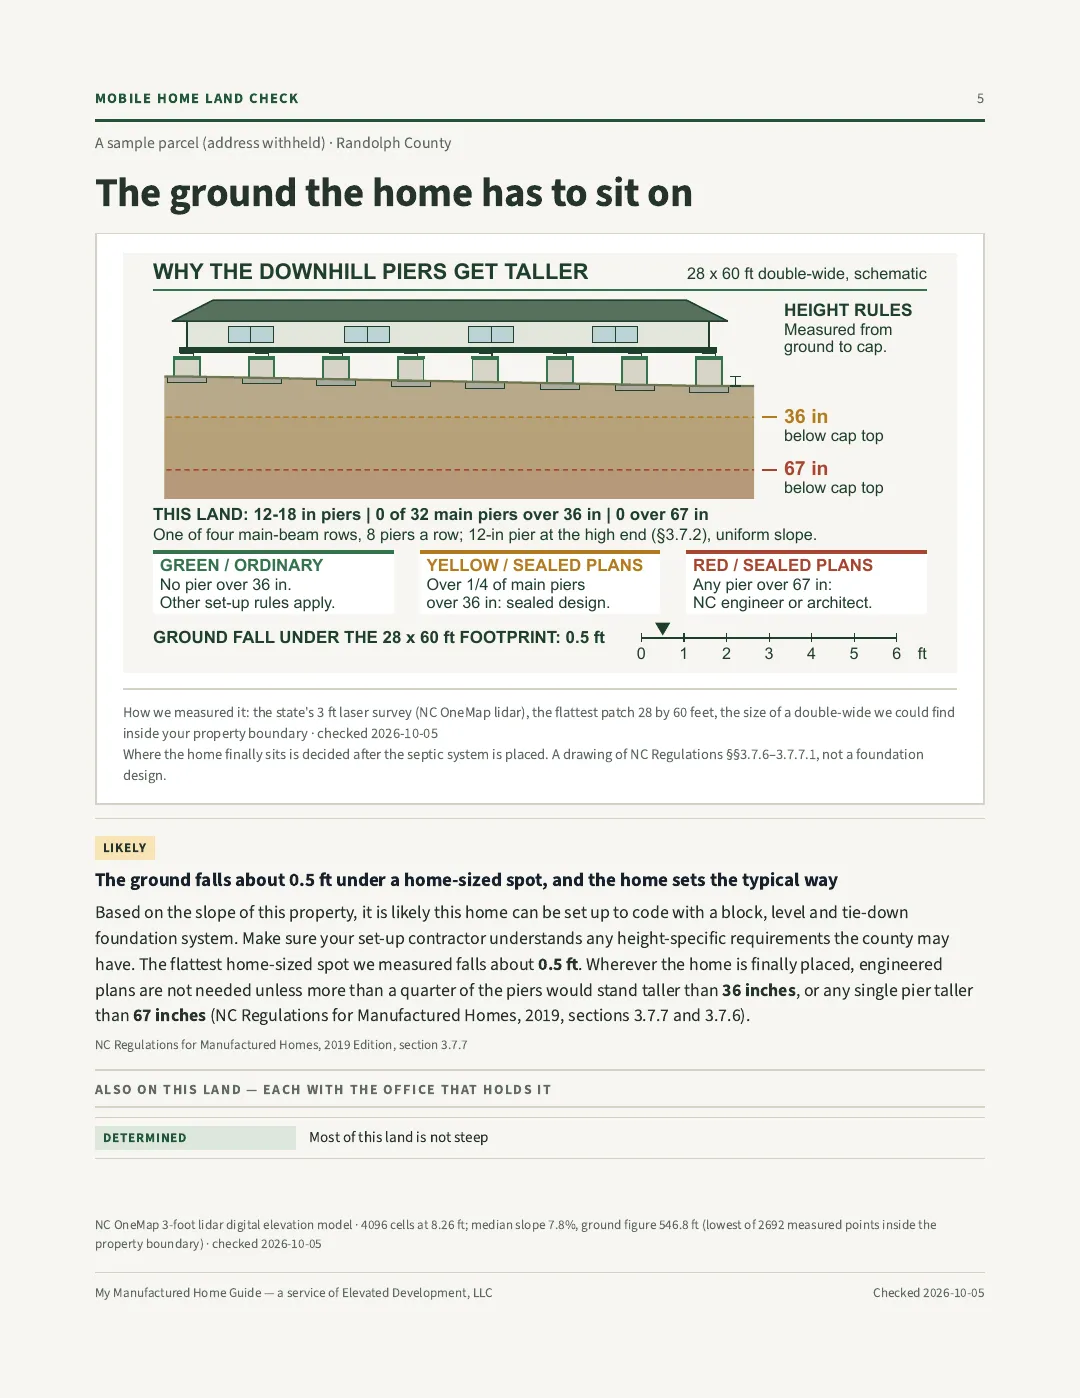
Page 5 — the ground and the pier plate
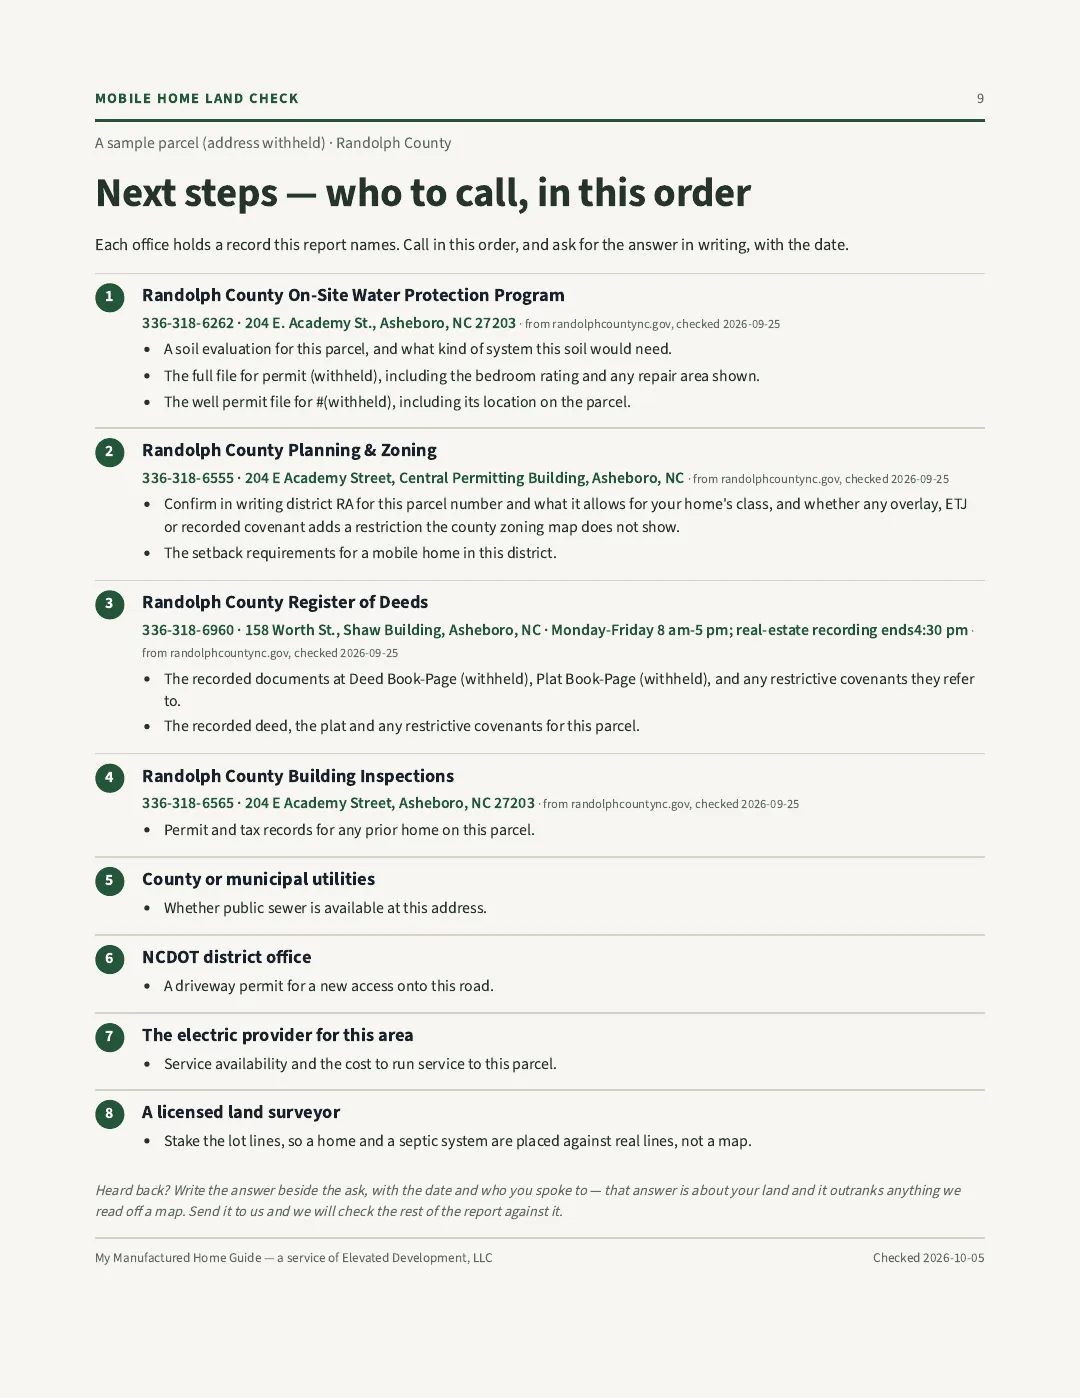
Page 9 — who to call, every office with its checked phone and address
It is not a customer’s report or a finding about your borrower’s land. For your file, start with the exact property, and include the proposed home dimensions and any specific site concern when you have them.
How a lender uses it
Step 1
Identify the property.
Use an NC property address, or the county and parcel/tax ID. Add the proposed home details and the question holding up the file if known.
Step 2
Choose who orders.
Order using your own contact details, or send your personal referral link to the borrower so they can request and pay directly. No loan application or financial documents are needed.
Step 3
Save the request, then pay.
Each property gets its own request and report. Keep the request reference with your file. Add your needed-by date so we can confirm timing.
Step 4
Put the findings to work.
Review the unresolved questions with the buyer and the relevant office or contractor. If the borrower orders, arrange for them to share the report with you.
Send the buyer a next step they can act on
When a borrower asks, “Can I put this mobile home on that land?”, give them a way to check before they commit. Ask for your personal referral link below, then share it with the borrower. They can identify their property, request the report, and pay for it themselves.
Before you commit to the land or home, get the site questions checked. This Land Check brings the available zoning, septic, flood, access and permit information into one report, with the next questions to resolve. Use the referral link I sent you to start with your property.
Talk to us about a file or request your lender link
Tell us where you work and what you need. We can help you start a property request or get a personal link to share with borrowers.
Questions from lenders
What does a Land Check tell a lender?
It puts zoning, setbacks, flood, septic and water, access, and permit questions for one NC property into a dated report. You see the available evidence, the questions still open, and who needs to confirm the next step before the file moves forward.
Does the report approve the property for our loan program?
No. Your lending requirements and underwriting decision remain yours. A Land Check identifies site questions; it does not replace an appraisal, title work, survey, engineering certification, site inspection, or an authority’s permit decision.
How do I order one for a file?
Start with one NC property address or county and parcel/tax ID. Use your own contact details, add the site question and planned home details if known, and submit the Land Check request. The request is saved before the payment step. Use a separate request for each property.
Can the borrower order through my link?
Yes. Share the personal referral link supplied to you so the borrower can request and pay for their own Land Check. Ask us for your link using the lender contact form. Referring a borrower does not automatically give you access to their report; arrange sharing with them.
Does this work for a used mobile home?
Yes. A used mobile home being moved needs the destination land checked too. Include its dimensions and known home details. The report addresses the land; the home’s condition and suitability for transport need their own review.
When should I request it?
Request it while site questions can still change the decision, before the buyer commits to the land or home. Include your needed-by date so we can confirm timing for the file.
Use the report alongside your required checks
Your underwriting requirements and loan decision stay with you. The report does not approve a loan or permit, certify a foundation, or replace title work, a survey, appraisal, flood determination required for your loan, or an onsite inspection. Use its findings to identify which evidence and decisions your file still needs.