My Manufactured Home Guide

Financing

How do I get a loan for a mobile home?

There are two families of mobile home loans, and which one you can use depends on whether the home is financed by itself or together with the land under it.

Short answer: A chattel loan finances the home alone, as personal property — it is how most homes in parks and on leased land are financed, and how a home is often financed when the land is already owned outright. A land-and-home loan, which can be a conventional or government-backed mortgage, finances the home and the land together as real property; it needs a permanent foundation and the home's title retired to the land. Lenders also look at the home's age, its HUD data plate, the foundation, and the site. This page explains the mechanics; it is not financial advice, and the lender's requirements decide.

Reviewed by a manufactured home setup contractor and dealer.

The foundation and setup a loan requires

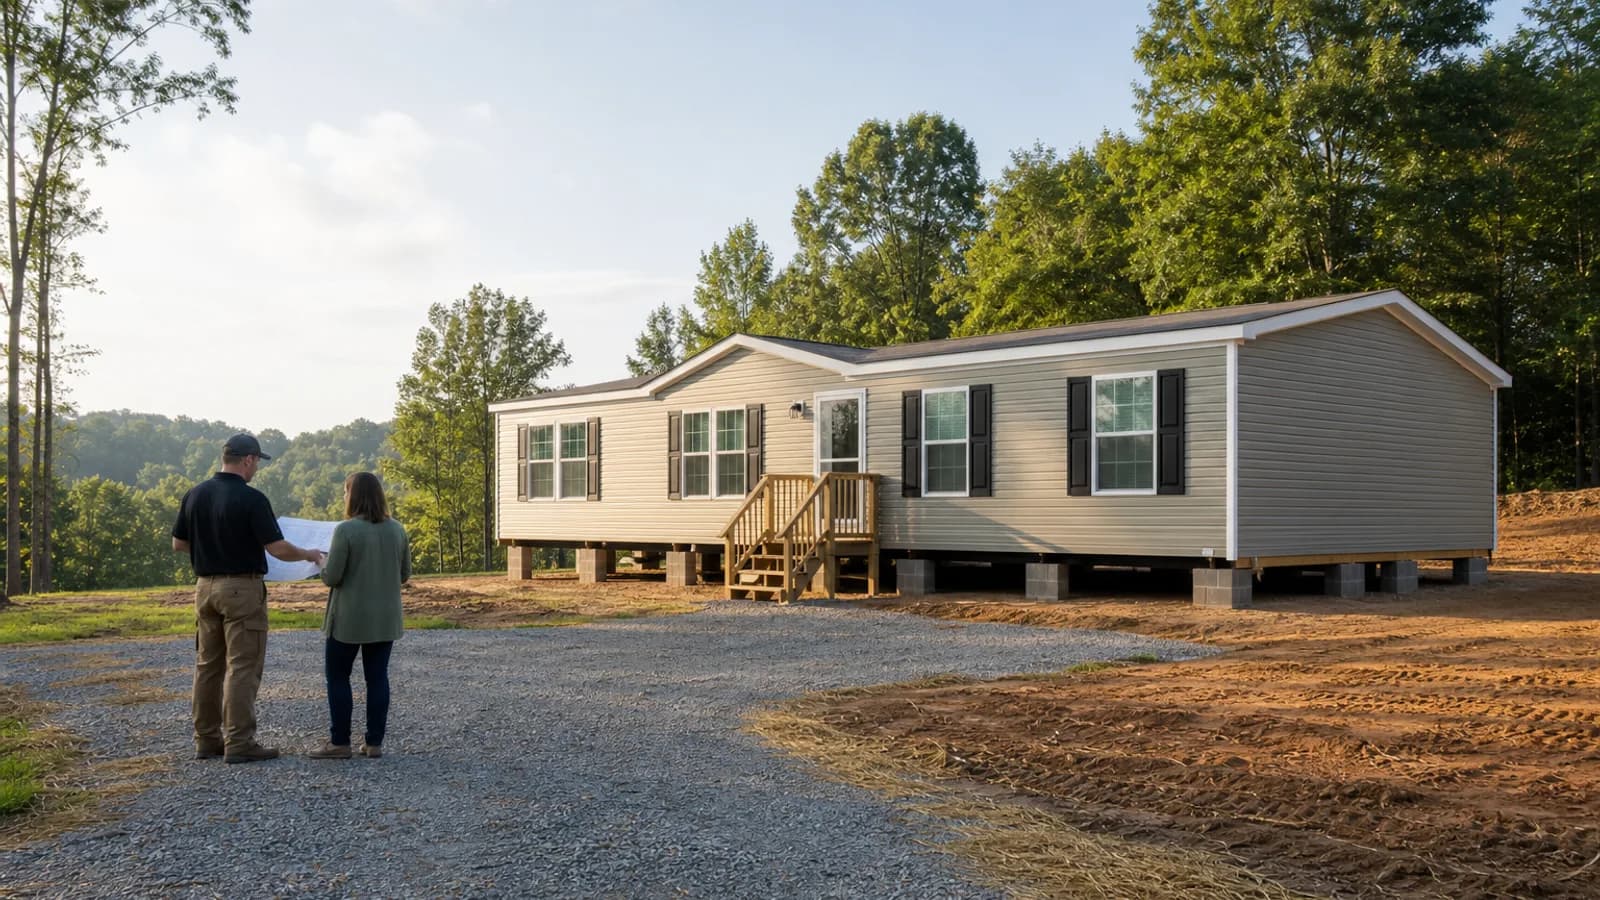
We are not a lender. But a loan comes with conditions on the installation — a land-and-home loan, which finances the home and the land together, needs the home on a permanent foundation — and the lender wants that work done and inspected. Ask your lender what foundation and setup the loan requires, then send it to us and we quote that work.

Tell me about your project. The quote is free.

I'll call you to learn about your project, then give you one price in writing for the work.

Phone or email — I need one to reach you
What do you need? Tap any that apply (optional).

You'll hear directly from me — the same person from the quote to the keys.

Prefer to talk?Call now8 AM–8 PM

What to check first

Start with the exact property, quote, record, or job detail behind your question. Mark what is confirmed, what still needs a current source, and who must answer it. Use the checklist to keep the next call, document, or decision clear.

Loan-program explanation, application, underwriting, disclosures, documentation, appraisal, and closing within the lender's role.

Clarification of land-home packages, home-only financing, existing-home transactions, or construction-related structures offered.

Written lender requirements for title, foundation, insurance, appraisal, installation, inspections, and completion.

Step 1

Borrower financial documents requested by the lender and a clear transaction summary.

Step 2

Land ownership or contract information, home quote, dealer details, site-work budget, and project timeline.

Step 3

Home make, model, year, dimensions, title status, installation plan, foundation concept, and insurance path.

Details to Sort

The checks that usually matter before you commit money.

Chattel loan or mortgage?

If the home will sit on land you do not own, or you want to finance only the home, the loan is a chattel loan and the home stays titled like a vehicle. If you are buying land and home together, or converting the home to real property, a mortgage becomes possible, and with it the requirements a mortgage carries: a permanent foundation to the lender's standard, a foundation certification, and the title retired at the county.

What the lender asks for

Expect to be asked for the home's year, make, model and serial number, the HUD data plate, the site address or parcel, whether you own the land, the dealer or seller's quote, and how the home will be set. Getting those together before you apply saves a round trip.

The quote is free. Tell us the job and the ZIP, and we call you.

Secondary Support

Need more help understanding your situation?

Not sure what work you need? Call now (8 AM–8 PM) or send the request: the quote is free, and the person who quotes your project runs it.

Free quote

Ask about mobile home lending

Share a few details to get an immediate starting point, likely next steps, useful guides, and relevant contractor categories. You do not need to know the exact permit or contractor type yet.

Add more project details (optional)

These details can help, but you can leave this closed if you are not sure yet.

Prefer to talk?Call now8 AM–8 PM

Common questions

Can I get a loan for a used mobile home?

Often, though lenders set their own age limits and condition requirements, and older homes have fewer options. A pre-1976 home — built before the HUD code — is the hardest case. Ask the lender for its age cutoff before you shop.

What is a chattel loan?

A loan on the home alone, as personal property, with the home's title as the collateral — the way a vehicle is financed. It does not require owning the land.

Do I need to own the land to finance a mobile home?

No. A chattel loan does not require it. Owning the land, or buying it in the same transaction, opens up mortgage financing, which has different requirements.

Can site work be financed with the home?

It depends on the lender, loan type, land status, and project structure. The key is to ask early before assuming site work is included.

Is FHA Title I the same as a mobile home mortgage?

Do not assume so. HUD describes Title I paths for manufactured-home units, lots, and combinations, including personal- or real-property situations. Ask the approved lender how its actual product is secured and closed.

Does a rural address mean a mobile home qualifies for USDA?

No. Area information is only one part of an official program and lender review. Borrower, occupancy, property, home, title, installation, appraisal, and current program requirements can also apply.

Can every VA lender finance a mobile home?

Do not assume a lender offers every VA-backed transaction. Start with the official VA benefit path, then ask the lender whether it currently offers the proposed mobile home or lot product and what requirements apply.

Is a land-home loan the same as a construction loan?

Not necessarily. Lenders use different products and closing structures. Ask the lender whether the proposed transaction is purchase, construction-only, construction-to-permanent, or another product and how land, home, site work, and completion are handled.

Will a construction loan pay every site cost?

Do not assume so. The lender decides which documented costs, providers, timing, contingencies, and change orders its product accepts. Compare that list with the complete project budget.

Does a Loan Estimate mean the project is approved?

No. The CFPB explains that a Loan Estimate describes expected loan terms after an application; it is not an approval or denial. Ask the lender which underwriting, property, appraisal, title, and completion conditions remain.

Call now· 8 AM–8 PM